Flooded or Forced From Your Home by El Niño Storms?
Forecasters call this winter's El Niño potentially historic for Southern California. If storm damage has hit your home, or your insurance company is delaying, denying, or lowballing your claim, Feher Law can review your options. The consultation is free and confidential, and you pay no fees unless we win.
- Storm water, mud, or debris damaged your home or belongings
- You were forced out of your home and are paying for temporary housing
- An insurance company is delaying, disputing, or undervaluing your claim
Get a Free, Confidential Claim Review
You May Have a Claim If
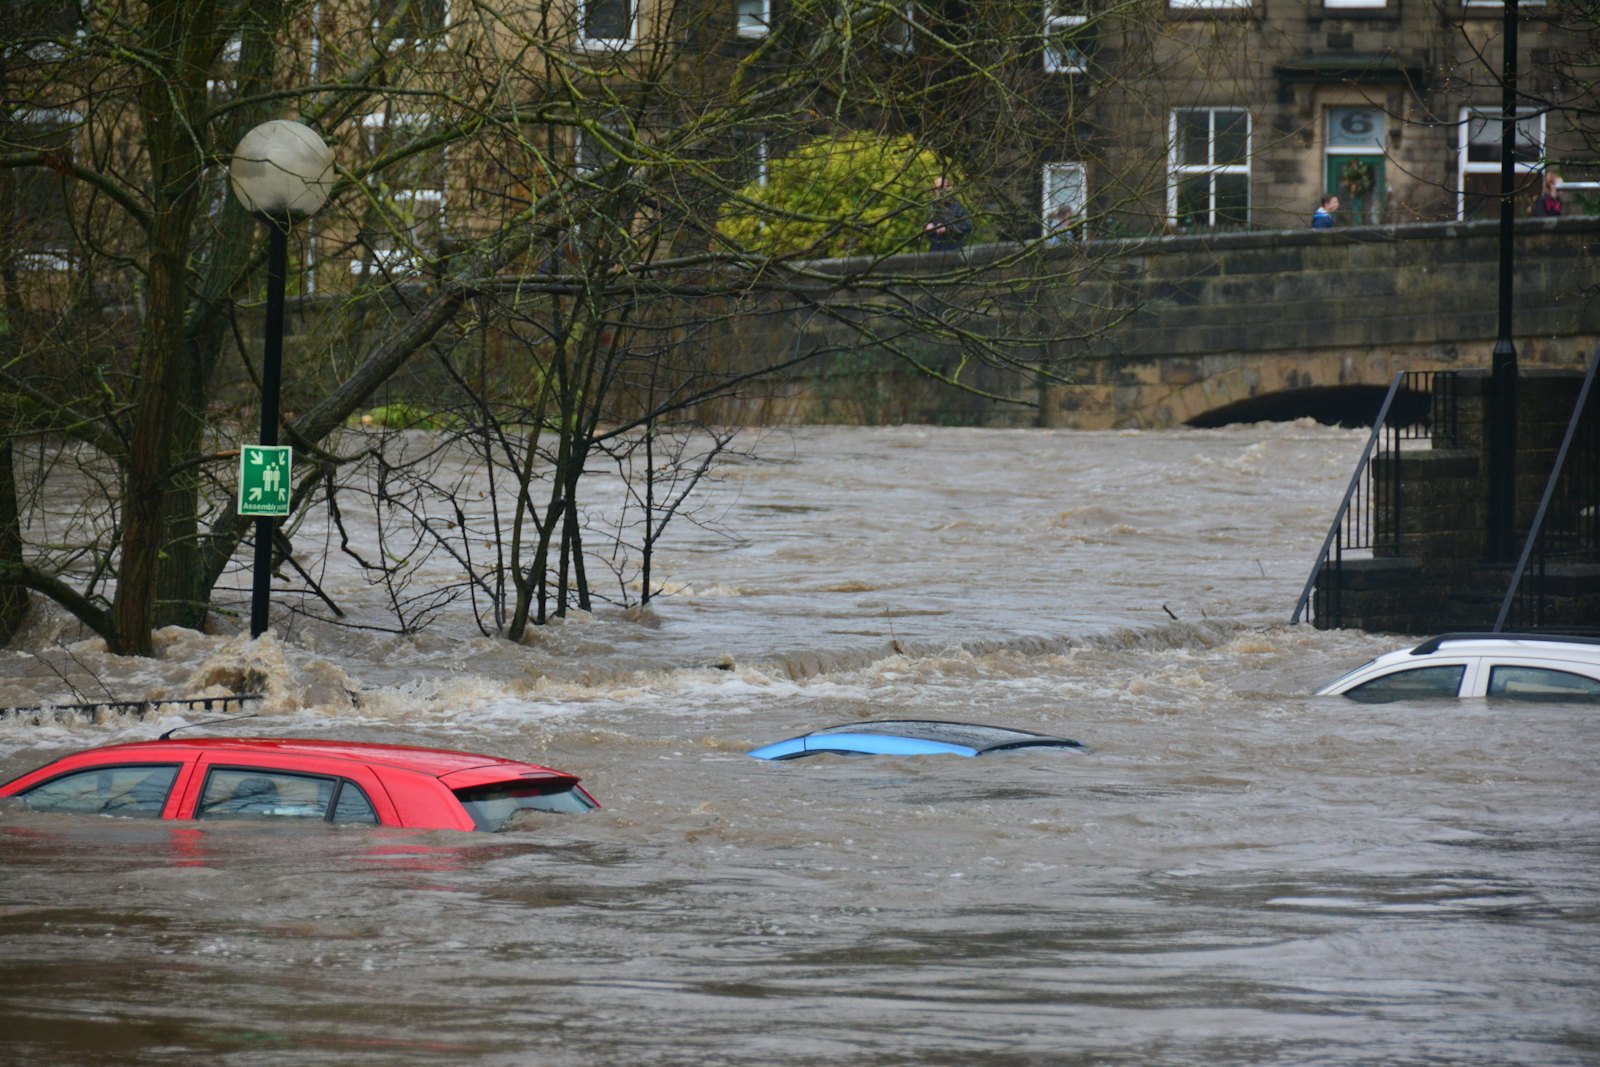
- Rain, flooding, mud, or wind damaged your home, garage, or belongings
- You are living in a hotel or rental and paying costs your policy should cover
- Your insurer is delaying the claim, disputing what happened, or offering less than repairs cost
- The water came from a failed storm drain, flood-control channel, or a neighboring property
- You or a family member was injured in a storm-related incident
What California Law Gives Storm-Damaged Homeowners
- Temporary housing paid by your insurer. When a covered loss is tied to a declared state of emergency, additional living expense coverage must run for at least 24 months under Insurance Code section 2060.
- Time to actually rebuild. For emergency-related losses, you have at least 36 months to collect full replacement cost under Insurance Code section 2051.5.
- The benefit of the doubt on cause. Under Insurance Code section 530, your insurer is liable when a covered peril is the main cause of the loss, even if an excluded peril played a lesser role. Insurers often cite the flood exclusion for damage the law says is covered.
- Fair claim handling. Your own insurance company owes you a duty of good faith. Unreasonable delay, lowballing, or denial can make the insurer liable for more than the policy itself.
- Claims against the government. If a public storm drain, road, or flood-control channel failed, a claim against the city or county must be filed within six months, and a dangerous condition of public property can make the public entity liable.
Why Feher Law
Trial-Ready Representation
More than 50 jury trials to verdict. Insurers value claims differently when the firm across the table tries cases.
Direct, Personalized Attention
You work with our team directly, in English or Spanish, and we keep you informed at every stage.
No Fee Unless There Is a Recovery
The consultation is free, and you pay no fees unless we win for you.
What to Do After Storm Damage
- Document everything before cleanup. Photos and video of every room, the water line, and damaged belongings are the backbone of your claim.
- Prevent further damage and keep every receipt. Tarps, water extraction, hotel nights, meals: reasonable costs are generally recoverable.
- Report the claim promptly and request a complete copy of your policy. You are entitled to it, and the exclusions matter.
- Get your own repair estimates before accepting the adjuster's number.
- Speak with an attorney early. Government claims can be due in six months, and policies set short deadlines to sue.
Frequently Asked Questions
Does homeowners insurance cover El Niño flood damage?
Standard homeowners policies exclude flood, which is separately insured through the National Flood Insurance Program, and NFIP coverage generally takes 30 days to take effect, so waiting until the storms arrive is too late. But the exclusion is not the end of the analysis: California's efficient proximate cause rule (Insurance Code section 530) makes the insurer liable when a covered peril, such as wind damage or a rain-driven roof failure, is the predominant cause of the loss. Many denied storm claims are actually covered. Have a lawyer read the denial before you accept it.
Who pays for our hotel and living costs if we cannot stay in the house?
Your own policy's additional living expense (ALE) coverage pays the reasonable increase in what it costs to live away from home: lodging, meals above normal, mileage, even pet boarding. When the loss relates to a declared state of emergency, California requires ALE coverage to run at least 24 months (Insurance Code section 2060). Keep every receipt from day one.
What if my insurance company delays, lowballs, or denies my claim?
California law requires your own insurer to investigate promptly and handle your claim fairly and in good faith. When an insurer unreasonably delays payment, undervalues repairs, or denies a covered claim, it can be liable for far more than the policy benefits, including your consequential losses. Document every call and letter, and get a free review before accepting a low offer.
The flooding came from a storm drain or flood-control channel. Who is responsible?
When a public improvement such as a storm drain, culvert, or flood-control channel fails or is inadequately maintained, the city, county, or flood-control district may be liable for a dangerous condition of public property, and inverse condemnation can apply when a public work causes the flooding. These claims run on a much shorter clock: a written government claim is generally required within six months. If a neighboring property's grading or construction sent water onto yours, the responsible owner or contractor can also be liable.
What deadlines apply to storm damage claims?
Three different clocks can run at once. Insurance policies require suit within 12 months of the loss, extended to 24 months when the loss relates to a declared state of emergency (Insurance Code section 2071). Government claims are generally due in six months. And lawsuits against private parties for property damage generally must be filed within three years. The safest move is an early, free review of which deadlines apply to your situation.
How much does it cost to hire Feher Law?
Nothing up front. The consultation is free, in English or Spanish, and we are paid a percentage of the recovery only if we win. If there is no recovery, you owe us no attorney fee.
Get a Free, Confidential Claim Review
Available 24/7. No fees unless we win.
Get My Free Claim ReviewCall (310) 564-0562